Investing.com — The U.K. stock market is losing relevance for retail investors as companies leave London and the pool of recognizable names shrinks, according to Nick Saunders, chief executive of Webull U.K.
“The UK market is approaching irrelevance, as fewer quoted stocks, particularly fewer household names, lowers market participation,” Saunders told Investing.com.
His comments come as more London-listed companies moved towards exiting the market on Tuesday.
has recommended an all-cash offer from U.K. private equity firm Epiris, has backed a cash takeover by Norway’s DNO ASA, while has agreed a takeover by U.S. investment firm Veritas.
Companies departing the London market cause both institutional and retail investors to stop looking for opportunities in the U.K., Saunders said, with lower interest feeding through to lower liquidity.
Webull U.K. began offering U.K. equities at the start of the year. Saunders said single stocks in the U.K. hold little interest for retail clients, with larger names sometimes forming part of a broader portfolio but attention concentrated on the U.S., where investors see the potential for a breakout small cap.
“Stamp duty is the real killer for retail investors,” he said, referring to the 0.5% charge on U.K. share purchases that does not apply to U.S. equities.
However, appetite is said to remain for U.K.-listed exchange-traded funds, particularly within long-term investment strategies.
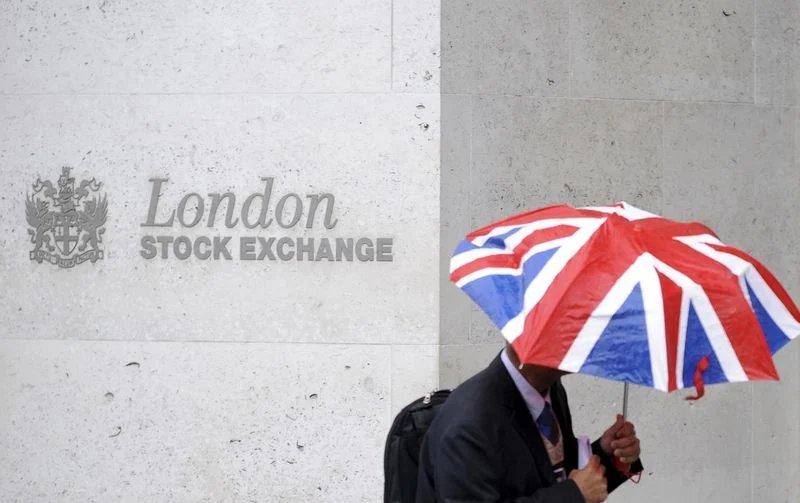
Saunders was sharply critical of London Stock Exchange Group’s priorities. Asked whether the incentives of a business now weighted toward data and analytics align with building a deep retail market in U.K. equities, he said the opposite was true.
” has for several years been more concerned with revenue from selling data products than investing in a functioning market,” he said. Recent reductions in the cost of retail price distribution help, he added, but do little to encourage participation.
On proposals to extend U.K. trading hours, Saunders argued the effect would be to stretch existing liquidity rather than create new liquidity.
He described the mechanism as a decline in liquidity density, where the same number of shares change hands, but orders are spread across a longer period, leaving the order book shallower at any given moment.
“Market makers and institutional traders do not double their risk capital just because the clock says they should,” he said. “They allocate the same risk budget across a longer day.”
The consequence, he believes, is that a market maker filling an order holds inventory for longer before finding a counterparty, increasing the risk that prices move against the position. Market makers compensate by widening spreads, raising the average effective cost of trading.
Furthermore, he feels execution quality would diverge by order type. Market orders would deteriorate, running through more price tiers to fill and producing execution prices materially worse than the touch price.
Limit orders would improve marginally, competing against fewer resting orders across a wider spread, but with a lower probability of being filled, and potentially sit unexecuted for hours or expiring at the close.
Saunders noted that demand for longer access to U.K. stocks does exist, but is conditional on sufficient liquidity being available. Rising costs of trading in illiquid hours would eventually suppress that demand.
Concentrating liquidity into auctions could offset the effect, he said, while a continuous order book across extended hours represents a threat to liquidity and, in turn, to the exchange’s viability.