There’s a strong chance Nvidia makes up a bigger chunk of your pension than the UK stock market – and that’s why the scandal that has engulfed it and seen its superstar boss quit matters to you, explains Rachel Rickard Straus
When you’ve worked hard for every pound that you’ve saved, seeing hundreds or thousands disappear within days is hard to stomach.
Especially when the cause is something you’ve no control over.
The pensions and Isas of millions of British savers have been dented this week by the revelation that a middle-aged man thousands of miles away had an affair.
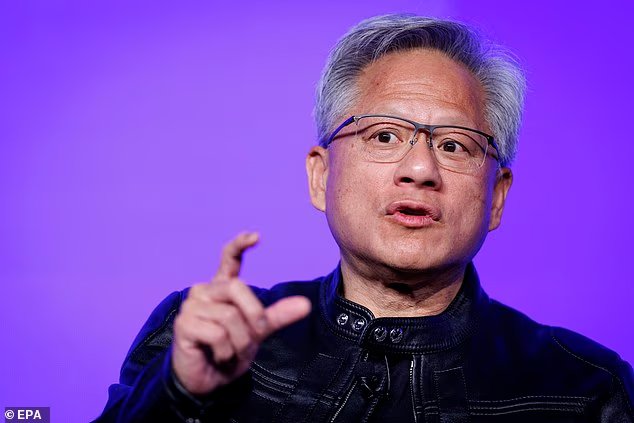
This week, shares in Nvidia have tumbled by £730billion as the company launched an investigation into its founder Jensen Huang over his affair with a suspected Chinese spy.
It has also been claimed since that he had an affair with a colleague. As a result, Mr Huang quit on Thursday, putting further pressure on Nvidia’s share price.
Nvidia’s share price has nosedived 30 per cent since its peak in early October. That’s a painful hit for those who invest directly in its shares, but also our pensions and Isas , as many of us will hold funds that feature a sizeable chunk of Nvidia.

Nvidia has now launched an investigation into boss Jensen Huang’s affair with a suspected Chinese spy
If you’ve never bought shares in Nvidia, you may wonder what its share price and boss’s infidelity has to do with you.
But Nvidia is such a behemoth that most of us own a stake.
As the second biggest company in the world, it alone accounts for 5 per cent of the value of developed global stock markets.
To put that in context, the entire UK stock market makes up about 3 per cent of the global stock market.
If you hold a global fund, a US or technology one, or are simply paying into a workplace pension – you will have a chunk of your savings in Nvidia.
I checked the value of my investments this morning – not pleasant – now wish I hadn’t.
The Nvidia share price tumble is just the latest dent. It had already been knocked in recent days by the rollercoaster ride technology stocks have been on since last week’s US midterm election results.
Against such a turbulent backdrop, the Government’s proposals last week to take the responsibility for investing our savings at retirement out of our hands look remarkably appealing.
The idea it put forward is that instead of us each being individually responsible for managing our retirement savings, we’d pool them with others to be invested on our behalf and we’d all get a regular income.
Announcing the so-called ‘guided retirement’ proposals, pensions minister Torsten Bell said savers would be given the option of taking a stable income for the rest of their lives ‘without having to become investment experts overnight’.
We’d no longer have to think about stock market volatility, second-guess how long we might live for, or risk running out of money.

Rachel Rickard Straus: Nvidia is such a behemoth that most of us own a stake
Nvidia shares plummet? Wouldn’t be our problem. Global stock market rout? Let someone else worry about it.
For some people, these proposals may offer a neat solution – although for those who want a guaranteed income for life such an option is already available in the form of an annuity.
But think what will be sacrificed. Those who sign up under the new scheme will lose the flexibility and freedom to manage their retirement savings as they choose.
They won’t be able to take a chunk when they need it, take a little less another year when they don’t. There will be little scope for changing your mind.
And sadly we’ll be playing into the old, bogus narrative that investing is difficult and better left to the experts.
Eleven years ago we were handed pension freedoms to do with our pots as we choose. How disempowering to give it away again.
And what a failure if savers do not feel emboldened and supported to enjoy the freedoms we’ve been granted.
How much more empowering it would be if, instead of taking away savers’ agency by default, we invested in giving everyone confidence to make their own financial decisions.
Learning about money, saving and investing must start in schools. Talking about it should continue throughout a lifetime.
I’ve started to see the hoodie-wearing red squirrel of the Government and industry-led campaign to improve understanding of investing pop up all over billboards and on taxis. I wish him all the best, but I think it’s going to take more than that.
With a bit of confidence, even hair-raising times for financial markets needn’t be daunting.
If you are some years off retirement, you can take the likes of Nvidia and tech stock tumbles in your stride. Hopefully over the long term they’ll look like a blip. And you can rest safe in the knowledge that you’ll be buying at cheaper prices.
With confidence, older savers can stay on course and trust in the portfolios they have built.
Furthermore, those who are worried about stock market volatility have the option of taking out an annuity that offers a guaranteed income for life.
Rates have been hitting new records – a 65 year old with £100,000 can currently get an income of £8,209 a year for life.
They can get an income of £5,641 with inflation protection and with a guarantee of money returned if they die within five years.
Pension freedoms will fail if we rely on retirees to become ‘investment experts overnight’, as Torsten Bell put it.
What a terrible idea. But they will succeed if we become experts over a lifetime.
DIY INVESTING PLATFORMS
AJ Bell
AJ Bell
Easy investing and ready-made portfolios
Hargreaves Lansdown
Hargreaves Lansdown
Free fund dealing and investment ideas
interactive investor
interactive investor
Flat-fee investing from £4.99 per month
Freetrade
Freetrade
Investing Isa now free on basic plan

Trading 212
Trading 212
Free share dealing and no account fee
Affiliate links: If you take out a product This is Money may earn a commission. These deals are chosen by our editorial team, as we think they are worth highlighting. This does not affect our editorial independence.