But the two countries’ differences – fiscal, demographic and political – point to a longer recovery for China
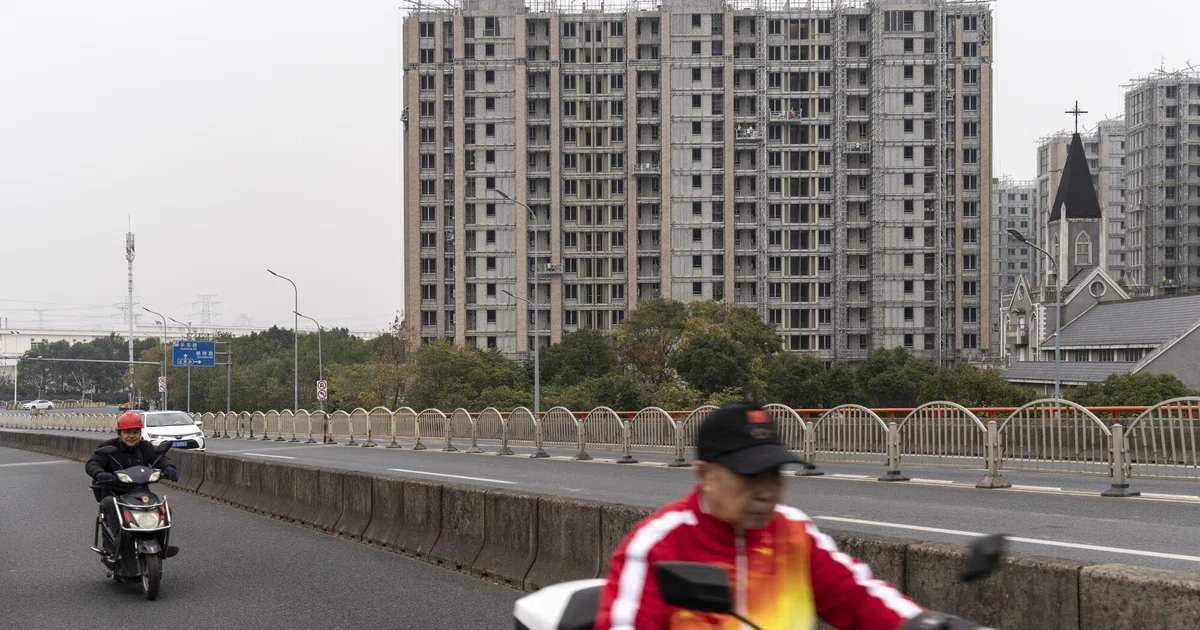
CHINA’S property sector, which accounts for nearly a third of aggregate demand, is now in its sixth year of contraction and shows no signs of any bottoming, let alone stability and recovery.
Property sales have collapsed by roughly 65 per cent from the 2020 peak. Construction activity has ground to its lowest level since 2000.
In the year to date through May 2026, residential sales volume declined by 16.2 per cent year on year, off an already low base in 2025.
On a recent trip I made to Lanzhou, the capital of Gansu Province, many residential apartments were visibly dark at night, empty save for a few occupied units. This is despite Lanzhou being arguably the most affordable provincial capital in China, with prices averaging 950 yuan (US$140.60) per sq ft in the city centre.
The current downturn therefore inevitably invites comparisons to two of the most devastating property slumps in history: Japan’s asset price bubble implosion of the early 1990s and the US subprime mortgage crisis that ignited the 2008 global financial crisis.
While each crisis was born out of similar DNA – excessive credit, rampant overbuilding and a collapse in asset prices and sales volumes – the differences in leverage structure, policy response and China’s unique institutional framework suggest its trajectory may be different from both the US and Japan crises.
Japan’s lost decade: the closest parallel
Both China and Japan share a structural feature that prolongs the pain: Housing is highly durable, and overinvestment during the boom simply cannot be unwound quickly. Excess supply hangs over the economy, discouraging new investment and weighing on activity long after volumes and prices peak.
When Japan’s property bubble burst in the early 1990s, real estate investment remained subdued for an extended period; it has yet to return to its pre-crisis level.
In Japan’s case, the boom was characterised by rapid expansion in residential and commercial real estate alongside infrastructure. In China, per capita housing stock had reached levels comparable to that in far richer economies by the late 2010s, with construction continuing even in shrinking Tier-3 cities.
SEE ALSO
The result in both cases is a long, grinding adjustment rather than a sharp V-shaped recovery.
The impact on China’s domestic consumption will likely be deep and painful, like the Japanese experience. Chinese households allocate nearly 70 per cent of their wealth to housing – a share far exceeding that of other countries – making them extraordinarily sensitive to price declines.
In a paper for the Brookings Institute, A Tale of Two Countries, 2026, Rogoff and Yang estimated that household consumption in China is far more sensitive to changes in house prices (elasticities of 0.15 to 0.23) than in Japan and the US.
A 40 per cent fall in house prices would imply an estimated total consumption loss of 2 to 4 per cent of gross domestic product, a magnitude that “far exceeds current policy measures aimed at boosting consumption”.
In Japan, home prices eventually declined by roughly 60 per cent from their peak. In China, official data reported a more modest 20 per cent drop. If the Chinese adjustment follows Japan’s path, it is not even halfway through the transition.
However, there are crucial differences too. In Japan, borrowing was concentrated in the corporate sector and private banks. In China, vulnerabilities are more concentrated in local governments and state-linked entities, particularly local government financing vehicles (LGFVs).
Japan’s property crisis was amplified by the 1985 Plaza Accord, which forced yen appreciation and eroded export competitiveness.
China does not face the same structural headwind, as total exports hit a record high of 14.7 trillion yuan in the first half of 2026, a 13.4 per cent year-on-year increase. It was the 11th consecutive quarter of year-on-year growth.
China also retains greater administrative capacity to postpone loss recognition and prevent outright financial sector collapse, enabled by a state-dominated financial system backed by implicit government guarantees.
And, unlike Japan in the 1990s, China is on the cutting edge of fast-growing sectors such as electric vehicles, renewable energy and artificial intelligence – productivity engines that could help prevent a full-fledged replication of Japan’s economic stagnation.
But the differences cut both ways. China is ageing faster than Japan did in the 1990s, and as a still-developing country, it lacks Japan’s extensive social safety net.
The International Monetary Fund warns that “significant deceleration of domestic demand heightens the risk of adverse macro-financial feedback loops”.
Furthermore, regardless of how dynamic they are, the newer growth engines remain small in comparison to real estate and infrastructure.
Rogoff and Yang said in their paper that “rapidly shifting from one export-led boom to another is unlikely to fully substitute for a domestic demand shortfall in an economy of China’s size”.
The Organisation for Economic Co-operation and Development (OECD) predicts that China’s growth will slow to 4.5 per cent in 2026 and 4.3 per cent in 2027, with medium-term growth falling to 3.5 per cent by 2030, unless concerted reform is implemented.
What history teaches us
The central lesson from Japan is that avoiding a banking crisis is not sufficient to ensure a swift recovery. In Japan, the financial channel intensified markedly during 1997 to 1998, but the real channels of investment, consumption and negative sentiment were already doing damage years before.
For China, this means that the property slump could persist even if the banking system is technically solvent.
The wealth effects on consumption, the drag on local government finances and the psychological scarring of households that have watched their main store of wealth slowly evaporate often work with a lag and can outlast any financial stabilisation.
If China’s path is comparable to Japan’s, the adjustment could span many more years.
Any straightforward historical analogy is complicated by China’s distinct institutional features, which include the state-dominated financial system, the hukou household registration system that limits internal migration, the fiscal reliance of local governments on land sales, and the demographic cliff that is approaching more quickly than Japan’s.
The property sector may no longer drive growth, but how China manages its retreat from this once-dominant sector will shape its macroeconomic trajectory for years to come.
The ghosts of Japan’s property crisis loom over China’s policymaking. But China is writing its own chapter in the history of property busts, and the ending is yet to be written.
The writer is chief investment officer Asia, Pictet Wealth Management