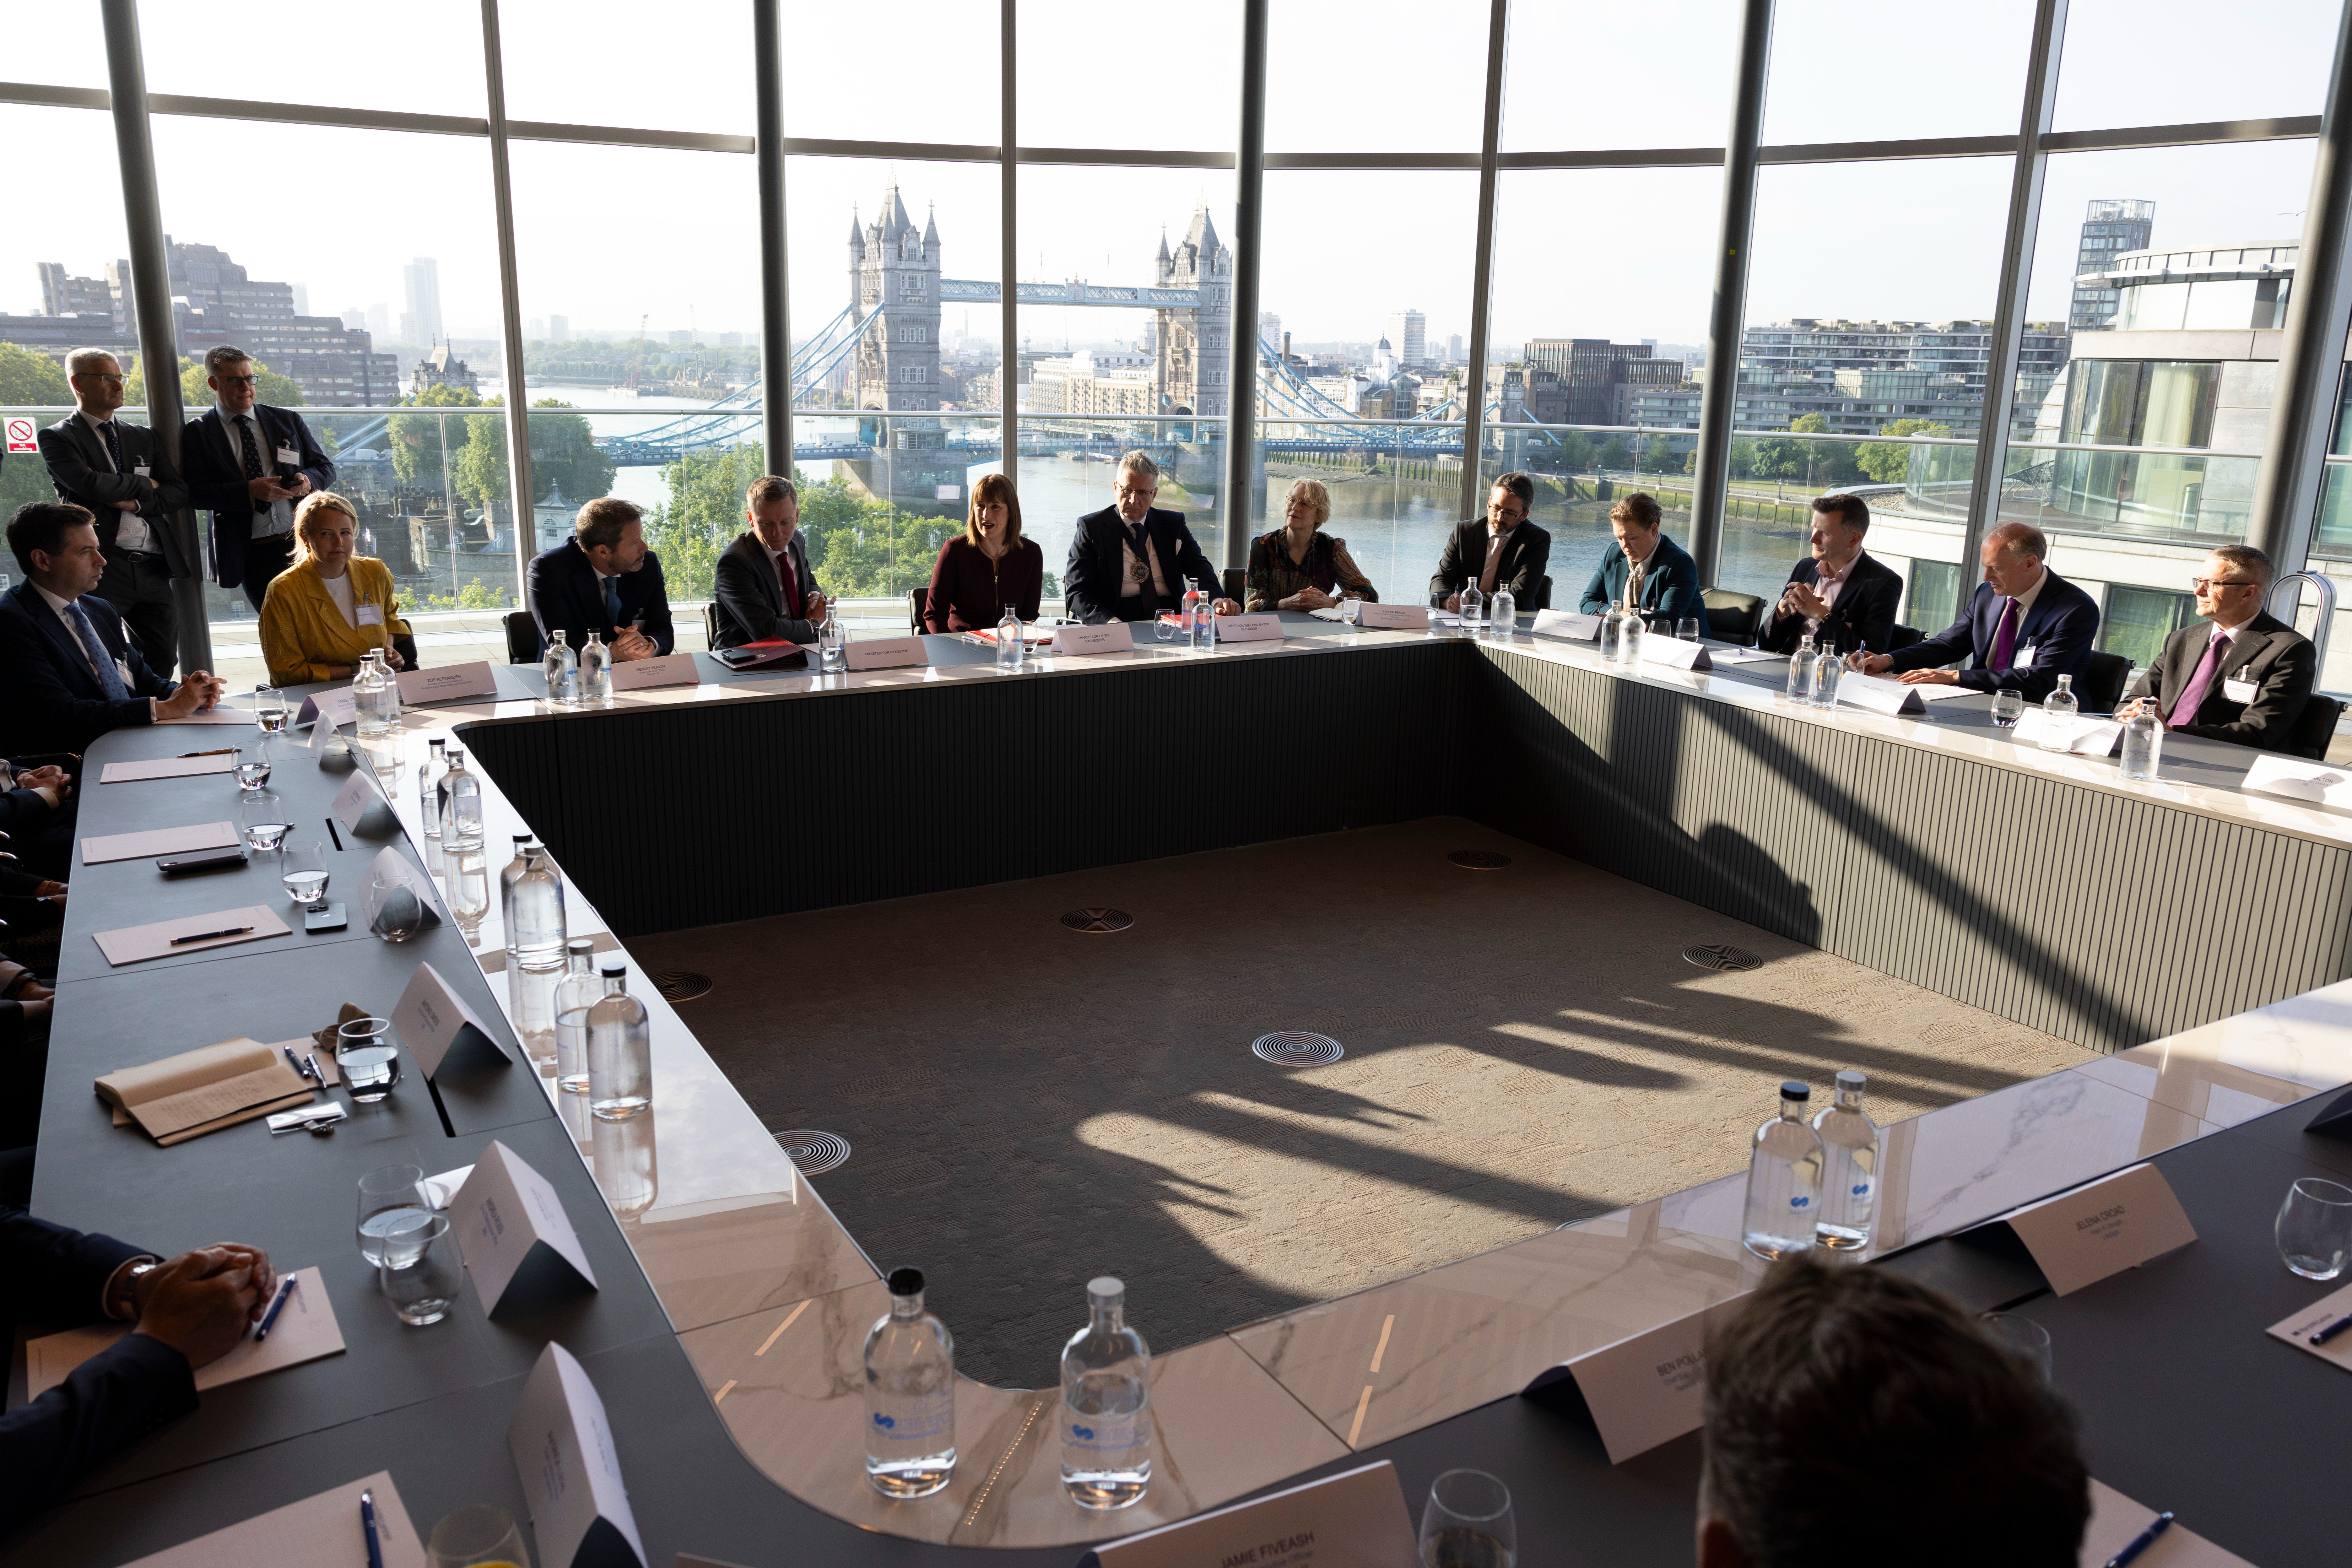
In 2025 workplace pension providers gathered at a roundtable in London to sign a voluntary agreement on investing in private markets.
Joined by then chancellor Rachel Reeves and pensions minister Torsten Bell, the 17 providers committed under the Mansion House Accord to invest at least 10 per cent of their defined contribution default funds in private markets by 2030.
Within that, at least half is to be allocated to the UK.
Analysis by the Association of British Insurers and Pensions UK, which lead the Accord alongside the City of London Corporation, shows that signatories at the end of 2025 held 6.6 per cent (£22.1bn) of DC growth-phase assets in private markets, with 3.3 per cent in the UK.
Of the £11.1bn invested in UK private markets, the majority (£8bn) was invested in property and real estate.
Across their wider DC asset base, signatories held £56.9bn in private markets.
“It’s not surprising that DC schemes have focused on real estate and physical assets as they begin implementation of their Mansion House commitments, given the real structural barriers they have historically faced in accessing the innovation economy,” says Ian Connatty, deputy chief investment officer at the British Business Bank (BBB).
“The UK venture capital market is thriving . . . But schemes need routes into the market that work for them.”
At the end of 2025, signatories to the Accord managed £334bn of growth-phase DC default assets. But Connatty says that for funds managing at least £10bn, it is “not straightforward” to find venture opportunities of sufficient scale.
Ben Wilkinson, chief executive of Molten Ventures and chair of the UK Private Capital’s DC expert panel, also describes the £8bn allocation to UK property and real estate as unsurprising.
“Property and real estate are the two areas where pension funds have existing internal capability, such as dedicated teams and a long history of investment, and they are also asset classes where deployment at scale is achievable.
“Venture and growth equity require a different skill set and, in many cases, different structures through which pension capital can access the asset class. Building that capability will take time, so the current figures are better read as an early-stage picture than as an indication of the ultimate opportunity.”
The Mansion House Accord says that signatories’ private market commitments depend on the government and regulators implementing “critical enablers”. This includes a pipeline of UK investment opportunities.
Despite the dominating allocation to UK property, Wilkinson says investable opportunities in infrastructure, private debt, credit and equity are not lacking. “At Molten, we would describe ourselves as capital constrained rather than opportunity constrained.”
Ask FT Adviser
These insights do not constitute advice and should not be relied upon by users in making any specific investment or other decisions.
BETA feature — this feature is still being tested and developed
Capability within pension funds and higher upfront fees appear to be some of the barriers to progress, he says.
“A culture of assuming lower fees delivers better value persists among employers and advisers who select the pension schemes. This ignores the higher returns, net of fees, of these asset classes. Value for money regulatory reforms are ongoing and seen as essential to resolving this issue.”
Michael Moore, chief executive at UK Private Capital, an industry body, likewise says that cost and a lack of a pipeline of investable businesses cannot continue to be used as “excuses” for lack of progress.
“British pension funds have the second-biggest private capital hub in the world on their doorstep. On average, 16 times more pension capital from around the world goes into private capital funds than UK pension capital, demonstrating both the breadth of investable opportunities and the strength of the investment case.
“Working closely alongside the pensions industry, we have identified ways to remove barriers to DC funds investing in private capital.”
Moore cites the Financial Conduct Authority’s expected consultation on the pension charge cap, changes that could be made to the regulator’s ‘permitted links’ rules that aim to protect retail-like investors from higher-risk, illiquid assets, as well as a marketplace proposed by UK Private Capital to facilitate investment into venture and growth capital funds by UK pensions.
Connatty from the BBB says there is “clearly a long way to go” to meeting the Accord’s targets. “But work to overcome these barriers is gathering pace, with more managers developing products that meet the needs of DC schemes.”
The BBB has itself launched a British Growth Partnership fund, which it says aims to address structural barriers and help pension funds increase their allocations to UK venture capital. In April the fund announced a first close at £200mn, which includes a first investment of £8mn into the UK self-driving company Wayve.
“Our experience launching the British Growth Partnership has shown us . . . that innovative DC investors who decide to access this market can do so,” says Connatty. “The bank is working closely with pension funds to build those routes and give them the confidence to invest.
“The first investment for any DC scheme is the hardest but once the infrastructure is in place, subsequent investments should become easier and the money can start to flow.
“We are starting to see that progress. Aegon UK and Cushon Master Trust made their first UK venture investments, directly from DC schemes, through the British Growth Partnership.
“The priority now is to build on those commitments and make investment in UK venture a sustained part of pension portfolios.”
Chloe Cheung is a senior features writer at FT Adviser