Operationalizing the new development model amid a deep downturn exposes at least four serious internal contradictions.
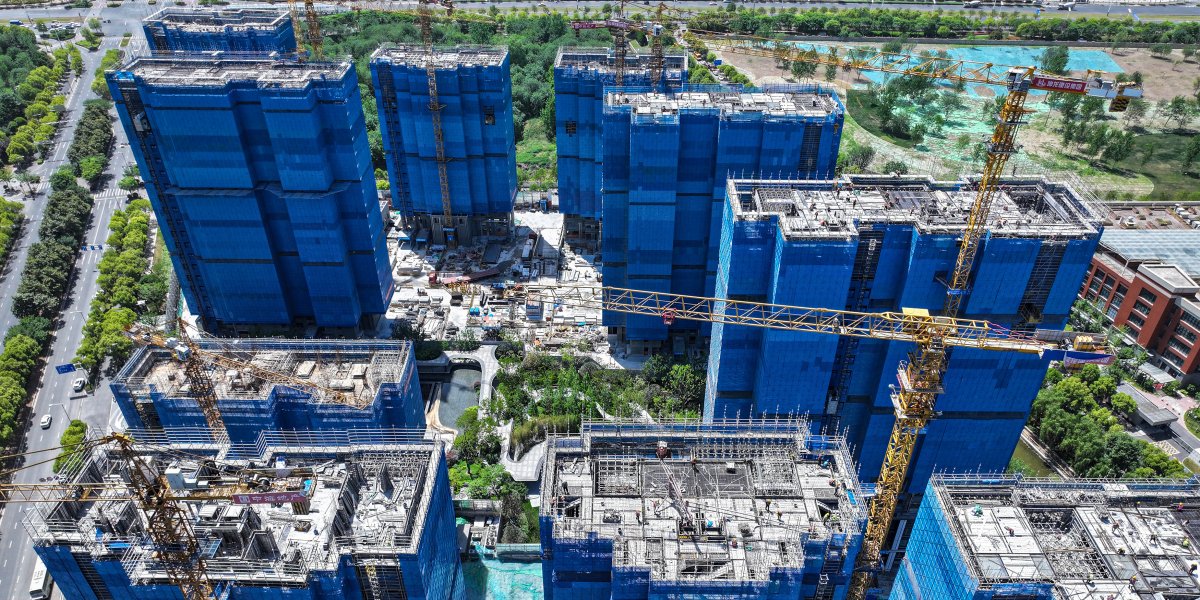
China’s overarching economic rebalancing strategy demands that the property sector shrink to free up resources for emerging, higher-value industries. But the depth and duration of the housing downturn have clearly exceeded policymakers’ expectations. The prolonged demand adjustment has pushed many developers into severe cash-flow stress, while the drag on growth, upstream and downstream industries, and employment has become far larger than Beijing appears willing to tolerate. As a result, policymakers have come to face a dual mandate: they still want to reduce the economy’s long-standing dependence on property, but they also feel increasingly compelled to arrest the downturn before its macroeconomic spillovers become too damaging.10
The evolution of Central Economic Work Conference (CEWC) language reflects this contradiction with increasing clarity. From 2019 to 2021, the emphasis remained on market stability, while the reform message was still framed in largely disciplinary terms through the slogan that “housing is for living in, not for speculation.” In 2022, amid deepening stress in the sector, the language shifted from curbing speculation to ensuring “stable development” and a “smooth transition” to a new development model. From 2023 onward, both imperatives were strengthened at the same time: the call to stabilize the market became more forceful, moving from “stable and healthy development” in 2023 to “halt the decline and restore stability” in 2024 and “stabilize the real estate market” in 2025, while the transition agenda also advanced from promoting a smooth transition to accelerating the development of a new model.
In effect, Beijing is now actively pursuing two objectives simultaneously: pressing ahead with a structural shift away from property-led growth, while also cushioning the fallout from that adjustment as its economic costs mount.
Another contradiction is between housing affordability and consumption. Lower housing costs free up household income for consumption, which is precisely what Beijing’s demand-led rebalancing requires. But in the near term, falling property values weaken household balance sheets and confidence, partially offsetting those gains.11 But those gains are likely to materialize only gradually. In the near term, falling property values can heighten households’ sense of financial insecurity and weaken confidence in future income and wealth, thereby blunting the consumption boost from the post-Covid recovery and from Beijing’s various consumption-support measures. Broader signs of household caution can be seen in both the central bank’s quarterly depositor survey — which shows a rising preference for savings over consumption and investment—and in the sustained elevation of new household deposits in recent years, trends to which housing-market weakness has likely contributed (figures 3 and 4).
The financial system faces its own set of dilemmas. Real estate-related exposure — primarily residential mortgages, loans to developers, and commercial loans backed by property collateral — together accounted for around 38% of China’s banking sector assets in 2023.12 A protracted property downturn therefore threatens bank asset quality, intensifies developer distress through falling collateral values, and amplifies broader credit tightening across the economy.
To prevent the near-term risks of broader financial contagion, authorities have enlisted banks’ help in stabilizing the property sector. Those include, for instance, a property project “whitelist” mechanism launched in early 2024 to meet developers’ “reasonable financing needs,” under which commercial banks have approved over RMB 7 trillion in loans.13 In early 2026, authorities reportedly gave banks the green light to extend the maturities of whitelisted loans by up to five years, in anticipation of lingering repayment stress among developers.14 Banks are also being pushed to finance local government acquisition of unsold developer inventory.
But sustained forbearance toward the property sector carries long-term costs. The new development model envisions a more diversified and sustainable financing structure — including greater use of asset-backed securities (ABS) and real estate investment trusts (REITs) — that would reduce the sector’s reliance on traditional bank lending.15 The more banks are used to roll over property-related exposures or finance inventory destocking, the harder it becomes to shift credit toward the sectors meant to underpin China’s next growth model. Nonetheless, authorities appear set to push in both directions at once, leaving banks to absorb the costs of short-term stabilization while constraining the credit reallocation needed for longer-term structural transition.
Local government fiscal constraints complicate both property market stabilization and the transition away from land-finance dependence. Official data show that revenue from state land-use rights transfers fell from RMB 8.49 trillion in 2021 to RMB 4.15 trillion in 2025 — a drop exceeding 50% (figure 5). In China’s fiscally centralized system — where revenue collection is relatively centralized, but expenditure responsibilities are largely borne by local governments — this collapse has materially reduced local governments’ capacity to support public spending, infrastructure investment, and hidden-debt resolution.
To shore up housing demand, local governments have rolled out homebuyer subsidies and preferential housing policies for targeted groups such as talent workers and multi-child families. Central tax incentives for homebuyers also translate into weaker local tax receipts in practice.16 Meanwhile, the push to acquire unsold commercial housing for conversion into affordable housing requires local SOEs to borrow heavily from banks, often with local fiscal support filling the gap.
The new development model imposes additional fiscal burdens. The “three major projects,” including urban village redevelopment and affordable housing construction — depend heavily on local fiscal capacity.17 Local governments are expected to provide matching funds, while land for affordable housing is commonly allocated rather than sold, limiting any immediate fiscal return. At the same time, pilot efforts to reform land supply in support of industrial policy — including greater use of leasing and other more flexible industrial land arrangements — point to a further weakening of land sales as a quick fiscal windfall.
Beijing has eased some of the pressure through higher local debt quotas and larger central transfers, but these measures are stopgaps.1819 The more durable solution would be to create a new and sustainable local revenue source to replace lost land-sale income. Yet here too, short-term stabilization collides with long-term reform objectives. The long-overdue property tax reform is the clearest example, as imposing one while home prices are still falling would intensify negative wealth effects and risk accelerating the very price declines Beijing is trying to arrest. This tension helps explain why property tax reform has remained stuck at the level of principle and planning: the 14th FYP’s pledge to “advance property tax legislation” has made no visible progress, while the recently unveiled 15th FYP drops any direct reference to a property tax altogether.20
Taken together, nearly every element of Beijing’s property reform agenda involves a tradeoff between medium-to-long-term structural health and short-term macroeconomic stabilization.